
Instant Borrow - Cash Now
- Rating
- 4.7
- Downloads
- 500.00K
- Content Rating
- Everyone
Instant Borrow - Cash Now - Screenshots
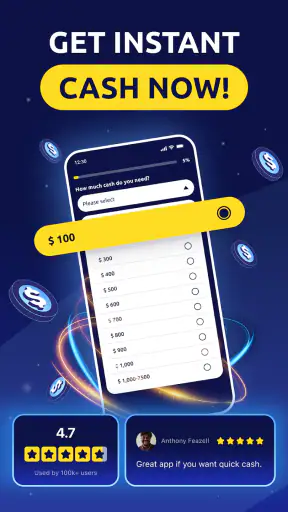
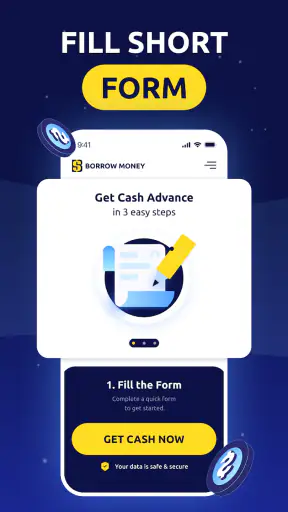
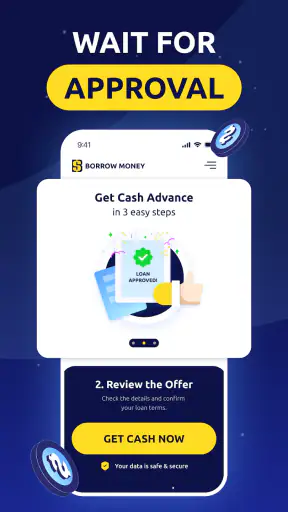
Pros
- Fast application process with minimal paperwork
- Clear repayment schedule shown before accepting a loan
- Useful for covering unexpected short-term expenses
- Available from a mobile device at any time
- Loan details can be reviewed within the app
Cons
- Approval and loan availability may depend on eligibility
- Fees and interest can make borrowing expensive
- Late payments may lead to additional charges
- Short repayment periods can strain your budget
- Availability and terms may vary by location
Instant Borrow - Cash Now - Description
- App Name
- Instant Borrow - Cash Now
- Package Name
- instant.borrow.app.get.cash.now
- Developer
- LM GROUPS
- Category
- Finance
- Last Updated
- Mar 13, 2025
- Version
- 1.0.5
When an unexpected expense lands between paydays, the hardest part is often not the amount itself but the time pressure. Instant Borrow - Cash Now is a finance app from LM GROUPS built around that exact moment: getting a borrowing request started without turning it into a long, confusing process. I found its appeal easy to understand. The app is free to install, aimed at everyone, and its central promise is speed rather than complicated money management.
That focus makes it different from a budgeting app, a traditional bank application, or a credit card dashboard. It is designed for a short-term need, not for tracking every part of your financial life. In my experience, that narrow purpose is both its main strength and the first thing a potential user should consider. If you need a quick route to explore emergency borrowing, it may feel more direct than the usual alternatives. If you are trying to build savings or reduce debt, it is not a replacement for those tools.
How the basic borrowing workflow feels
The first useful habit is to treat the app as a place to review an option, not as an automatic solution. I would open it only after deciding how much is genuinely needed and when repayment could fit into my normal budget. That small pause matters because a fast application can make an urgent decision feel easier than it really is. The app can streamline the request, but it cannot make an unaffordable repayment affordable.
The starting point is intentionally simple. You move through the borrowing process, provide the information requested by the app, and review the result before deciding what to do next. The cleanest way to use it is to keep the details consistent with your real financial situation. Rushing through fields with guesses or optimistic estimates may save a minute at the start but can create confusion later.
For a realistic example, imagine a necessary household repair appearing just before a salary payment. I would first write down the repair cost, check the balance already available in my account, and decide the maximum amount that would still leave room for food, transport, and existing bills. Only then would I use Instant Borrow - Cash Now to explore whether borrowing is suitable. This workflow keeps the app in its proper role: a tool for reviewing a possible short-term option rather than a reason to borrow more than planned.
The app’s free price removes one barrier to trying the interface, but free access should not be confused with free borrowing. The important financial details are the terms presented during the process, including the amount to repay and any conditions attached to an offer. I would read those details slowly, even if the app itself is designed to move quickly. A short wait saved today is not worth an unpleasant surprise later.
One practical advantage is that the app gives people a dedicated place to begin instead of forcing them to search through unrelated banking screens. Someone comparing several possible routes can use it as one point of reference alongside a bank, a credit union, or an existing card. I would not make it my only source of information, especially for a larger expense. The right comparison is the total repayment, the timing, and the consequences of missing a payment—not merely how quickly an application starts.
There is also a useful distinction between an urgent need and a recurring shortage. If the same problem appears every month, repeating a borrowing request is a warning sign rather than a successful routine. In that situation, a budgeting tool, a conversation with a bank, or a debt adviser may be more appropriate. Instant Borrow - Cash Now is more convincing when the expense is unusual and the user has a credible plan for handling the repayment.
What I would check before submitting anything
I would prepare the information the app is likely to need before beginning, while avoiding the temptation to enter details on a public or shared device. A stable internet connection, accurate contact information, and access to the financial details required by the screen can make the process less frustrating. I would also keep a record of the request and any final terms shown, because personal notes make later comparison easier.
Another good habit is to stop at every review screen. Fast finance apps often encourage a smooth forward motion, but the review stage is where I would check the requested amount, repayment timing, and whether the result matches what I intended. If the available option is larger than necessary, I would not assume that taking the maximum is sensible. Borrowing only the amount tied to the actual expense usually makes the decision easier to evaluate.
People often ask whether a fast borrowing app guarantees approval. I would not approach it with that expectation. A request still depends on the app’s process and the information supplied, so the sensible mindset is to apply for consideration, not to count the money before a final result is shown. That distinction is especially important when a bill is due soon. I would keep a backup plan ready rather than relying on an unconfirmed application.
The app is suitable for an adult who understands the responsibility of short-term credit, even though its content rating is Everyone. An age label describes the app’s general suitability; it does not remove the need to understand financial agreements or eligibility requirements. I would encourage younger users to involve a responsible adult and would advise anyone uncertain about borrowing to seek independent guidance before proceeding.
Settings and repeatable habits that make the experience safer
There may not be a reason to change every available option immediately. My approach would be to review the app’s permission and notification choices when installing it, allowing only what is needed for the experience I actually want. Notifications can be useful for reminders or status changes, but too many finance alerts can create pressure. I prefer to keep important updates visible while avoiding a stream of prompts that encourages impulsive borrowing.
I would also check the device’s notification settings rather than assuming the app alone controls everything. On a shared phone, previews might expose sensitive financial information on the lock screen. Turning off message previews or using a secure device lock is a simple privacy improvement. This is not a glamorous feature, but it is one of the more valuable habits for any finance app, particularly one connected with borrowing.
Keeping the application current is another sensible step. Instant Borrow - Cash Now is listed at version 1.0.5, so I would look for updates through the official app store and install them when practical. Updates can improve stability or address compatibility issues, but I would still review any changed screens carefully after an update. A familiar button may move, and a new explanation may contain terms worth reading rather than skipping.
The developer is LM GROUPS, and I would use that name when checking that I had installed the intended application rather than an imitation with a similar title. This is especially important in finance, where lookalike apps can create unnecessary risk. I would avoid downloading a copy from an unfamiliar source and would never share account credentials through a message that appears unrelated to the normal app flow.
A helpful repeatable routine is to create a small borrowing checklist in my notes app. It would include the reason for borrowing, the exact amount needed, the date repayment is expected, and the total amount I am prepared to repay. After using Instant Borrow - Cash Now, I would compare the presented terms with that checklist. This turns an emotional decision into a short, repeatable process and makes it easier to notice when an option does not fit.
I would also set a personal cooling-off rule, even if the expense feels urgent. For a minor bill, that could mean reviewing the terms twice before accepting. For a more substantial request, I would compare the app’s option with my bank and any available non-borrowing alternatives. The app’s speed is useful, but speed should apply to navigation, not to skipping judgment.
One question many users have is whether the app replaces a bank account or a personal finance manager. In my view, it does not. It belongs beside those tools, not instead of them. A bank may offer a clearer view of existing funds, while a budgeting app can show whether a repayment will collide with upcoming bills. Instant Borrow - Cash Now is most useful as a focused borrowing channel within a wider money routine.
Faster patterns without losing control
Experienced use is less about tapping quickly and more about removing avoidable decisions. I would save the basic information needed for a legitimate application in a secure place, but I would not pre-fill an amount before knowing the expense. Preparing documents and checking account access in advance can make a genuine emergency less stressful without encouraging unnecessary requests.
Another efficient pattern is to decide the borrowing ceiling before opening the app. For example, I might say that I will not request more than the repair estimate plus a small, already-budgeted margin. If the app presents a higher possible amount, that ceiling remains unchanged. This is a simple form of self-control that works because the decision is made before urgency and interface prompts begin influencing it.
I would use the app at a calm time whenever possible, even when the expense itself is urgent. A quiet room and a few minutes to read the final screen are more valuable than completing the process while travelling or distracted. If a request is interrupted, I would restart carefully instead of assuming every field saved correctly. That small check can prevent submitting an outdated amount or an incomplete detail.
A second useful pattern is comparing the app with the alternative that is genuinely available, not an imaginary perfect option. If my bank offers a lower-cost way to cover the same bill, I would examine that first. If a trusted family member can help without creating strain, that may be preferable. If neither route is realistic, the app can still be considered, but only after looking at the complete repayment obligation.
The app has earned a 4.7 average from around twenty-six thousand ratings, with over five hundred thousand installs. Those figures suggest that many people find the experience useful, but they do not tell me whether a particular borrowing option suits my finances. I would treat popularity as a reason to inspect the app, not as proof that every offer or outcome will be right for me.
One trade-off compared with a traditional lender is convenience versus context. A bank may already understand more of my financial history and show borrowing alongside existing accounts, while a focused app may feel less cluttered when I need to start a request quickly. Conversely, a bank relationship may provide clearer support for a complex or larger financial decision. I would lean toward the bank for long-term borrowing and use this app only for a carefully bounded short-term need.
Compared with a credit card, the choice depends on the terms and repayment discipline. A card may be more convenient for a purchase and may already be part of a user’s routine, but it can also make repeated spending feel invisible. A borrowing app makes the immediate request more explicit, which I find useful psychologically. Neither option is automatically cheaper or safer; the total repayment and the user’s ability to clear it are what matter.
Where the limits become important
The biggest limitation is not necessarily a missing button or a difficult screen. It is the risk that convenience encourages repeated borrowing. An app that helps cover one urgent expense can become part of a cycle if it is used for groceries, subscriptions, or ordinary monthly bills. I would stop using it as a first choice if repayment depended on taking another advance.
I would also be cautious when the expense is uncertain. A medical, legal, or repair bill that may grow beyond the original estimate needs more planning than a quick request can provide. In those cases, I would ask the provider about payment arrangements and compare several funding routes before accepting anything. The app may start the process quickly, but it cannot replace negotiation or professional financial advice.
Privacy deserves attention too. Finance apps involve sensitive information, so I would read the app’s on-screen explanations and the store’s privacy details before continuing. I would keep the phone secured, avoid sending screenshots of financial pages, and remove access from devices I no longer use. These steps are easy to overlook when the main concern is getting money quickly.
Users should also understand that the free download is only one part of the financial decision. I would never judge affordability from the installation cost. The meaningful question is what the borrowing arrangement requires me to repay and when. If the terms are unclear, difficult to locate, or unlike what I expected, I would pause instead of accepting simply because I had already completed most of the application.
The release date is Mar 13, 2025, which places the app in a relatively new stage of its life compared with long-established financial services. That does not make it unsuitable, but it makes careful checking more important for me. I would pay attention to how stable the current version feels on my device and keep alternative ways to handle an urgent bill. Newer software can be perfectly usable while still benefiting from time and user feedback.
There is also a practical support question. If an application becomes stuck or a result takes longer than expected, I would avoid submitting multiple requests in frustration. Duplicate attempts can make personal records harder to follow and may lead to unnecessary confusion. I would first check the app’s status information, review any messages, and use the official support route associated with the service. Patience is part of safe use when money is involved.
Who should skip it? I would say anyone looking for investment tools, detailed spending analysis, savings goals, or a permanent replacement for a current account. It is also a poor fit for someone who cannot identify a realistic repayment source. A free finance app can be useful, but it cannot solve an income gap that has no clear end. In that situation, a nonprofit debt service or direct conversation with creditors is likely to be more helpful.
My final view after using it as a focused tool
Instant Borrow - Cash Now is best understood as a quick starting point for a short-term borrowing decision, not as a shortcut around financial planning. I like the focused purpose, the free entry point, and the straightforward idea of dealing with an urgent expense in one dedicated app. The experience makes sense for someone who has a specific need, knows the amount required, and can assess repayment without guessing.
My recommendation comes with firm conditions. I would install it for comparison, check the developer name, review permissions and notifications, and prepare a borrowing limit before beginning. I would then read the complete terms, compare them with a bank or other realistic alternative, and save a personal record of the decision. Those habits reduce the chance that a fast interface will turn a temporary problem into a longer one.
The app’s Everyone rating and broad reach make it approachable, but approachability should not be mistaken for suitability in every situation. The people most likely to benefit are adults facing an isolated, urgent expense who value a simple application path. The people most likely to regret using it are those borrowing for routine living costs or accepting an amount without checking the full repayment obligation.
After weighing those trade-offs, I see Instant Borrow - Cash Now as a useful specialist rather than a complete financial companion. It can save time at the beginning of an emergency decision, and that is meaningful when a bill cannot wait. Still, the strongest feature is the discipline the user brings to it: a fixed amount, a clear repayment plan, careful reading, and a willingness to walk away when the numbers do not work. Used that way, it is worth considering; used impulsively, its convenience becomes the main risk.
FAQ
What is Instant Borrow - Cash Now and how does it work?
Instant Borrow - Cash Now is a financial app designed to help eligible users explore short-term borrowing options through a mobile device. After creating an account, you may be asked to provide personal, employment, income, and banking information. The app can then review your details and present available offers, although approval, loan amounts, interest rates, and repayment terms are not guaranteed.
Is Instant Borrow - Cash Now a direct lender?
Not necessarily. Apps in this category may operate as loan-matching or lead-generation services rather than lending money directly. Your application information may be shared with partner lenders or financial service providers that evaluate your request. Before accepting an offer, carefully check the lender’s name, annual percentage rate, fees, repayment schedule, and cancellation terms, since conditions can vary considerably.
What information is required to apply through the app?
During the application process, Instant Borrow - Cash Now may request identifying and financial details such as your full name, address, phone number, email address, date of birth, income, employment information, and bank account details. Only submit information through the official app or website, review the privacy policy first, and avoid providing sensitive data to unofficial copies or suspicious third-party pages.
How quickly can I receive money after applying?
The app may advertise fast decisions or quick access to funds, but the actual timing depends on several factors. These can include application verification, lender approval, banking hours, weekends, holidays, and the transfer method used. Even if you receive an offer immediately, funding may take longer, and approval does not guarantee that money will be deposited instantly.
What fees, interest, and repayment risks should I consider?
Before accepting any borrowing offer, review the complete cost rather than focusing only on the amount you could receive. Short-term loans may include high interest, origination charges, late-payment fees, or other costs, depending on the lender and your location. Confirm the total repayment amount, due dates, automatic-debit rules, and consequences of missing a payment to avoid unexpected financial pressure.


